Job Costing for Contractors: A Practical Setup Guide
Job Costing for Contractors: A Practical Setup Guide
Job costing for contractors means assigning every dollar of labor, material, equipment, and overhead to a specific job and cost code so you know exactly what each project earns, not what your bank balance guesses it earns. The immediate next step is simple: build a lean cost-code structure and start capturing field data daily, not at month-end. Integrated platforms like JobOS Pro can move that data from a delayed spreadsheet exercise into real-time visibility, which matters more than most contractors realize until they’ve bled margin on a job they thought was profitable.
Key Takeaways
Accurate job costing requires daily field data capture, burdened labor rates, systematic overhead allocation, and weekly estimate-versus-actual reviews to protect margin.
| Point | Details |
|---|---|
| Start with five to seven cost codes | Keep the structure simple at launch, then expand granularity once field capture is reliable. |
| Burden labor before bidding | Add 20% to 60% burden to base wages so estimates reflect true labor cost. |
| Budget 5% to 10% contingency | Reserve this range for straightforward projects to absorb unforeseen costs without eating margin. |
| Review estimate vs. actual weekly | Catch variance early rather than discovering losses at job close. |
| Preserve full WBS in your software | Choose a platform, such as JobOS Pro, that syncs cost codes to accounting instead of GL summary totals only. |
Table of Contents
- What Is Job Costing and Why Does It Matter for Contractors?
- Job-Costing Components: What You Actually Need to Track
- How Do You Set Up Job Costing From Scratch?
- How Do You Collect Accurate Job-Cost Data in the Field?
- How Do You Allocate Overhead and Calculate Labor Burden?
- What Software Features Do You Need for Accurate Job Costing?
- Which Reports and KPIs Actually Matter for Job Costing?
- How Does Job-Cost Data Improve Bidding and Operations?
- What Pitfalls Should You Watch for During Rollout?
- How Long Does It Take to Roll Out Job Costing?
- What Do the Benchmarks Say About Contingency and Burden?
- How Job Costing Looks Different Across Trades and Project Types
- How Do You Adjust Job Costs When a Project Changes?
- Who Should Own Data Entry, Monitoring, and Analysis?
- A Publisher’s Perspective on Integrated, AI-Assisted Job Costing
- How JobOS Pro Supports Real-Time Job Costing
- Sources
What Is Job Costing and Why Does It Matter for Contractors?
Job costing assigns direct and indirect costs to a specific project, giving each job its own profit-and-loss statement instead of lumping everything into one company-wide number. That distinction changes how you bid, how you manage cash, and how fast you catch a job going sideways.
Without it, job costing ties costs to individual projects and enables earlier detection of overruns, which directly improves both estimating accuracy and cash flow planning. A framework like CSI/MasterFormat gives you a standardized way to code that data. A work-in-progress (WIP) schedule turns it into a metric you can act on weekly.
Here’s how a “profitable” job turns into a loss:
- A remodel bids at $45,000 with $12,000 budgeted for labor.
- The crew works 320 hours at a $25/hour base wage, but the estimate never accounted for labor burden.
- Add 30% burden (payroll taxes, workers’ comp, benefits) and true labor cost jumps to $10,400 versus a base-wage calculation of $8,000.
- Overhead allocation adds another $3,500 that never made it into the original number.
That single missed burden calculation quietly erases the job’s margin before the first change order even hits.
Job-Costing Components: What You Actually Need to Track
Every job cost breaks into direct costs (tied straight to the project) and indirect costs (spread across your operation). Direct labor is often the largest variable expense and needs tracking at the cost-code level, not just the job level, because that’s where you spot which phase is bleeding money.
Here’s the breakdown:
| Cost Bucket | What to Include | Common Capture Point |
|---|---|---|
| Direct labor | Wages, burden, overtime by cost code | Mobile time entry |
| Materials | Lumber, fixtures, supplies, delivery fees | Receipts, PO matching |
| Equipment | Rental, fuel, depreciation, maintenance | Equipment logs |
| Subcontractors | Sub invoices, retainage, change orders | Invoice intake |
| Permits and fees | Inspection fees, licensing, bonding | Admin entry |
| Overhead/burden | Insurance, office costs, allocated indirect | Monthly allocation |
To calculate fully burdened labor, take the base wage and add payroll taxes, workers’ comp, and benefits as a percentage. Bid off the wrong number and you’ve already lost.
- List every worker’s base wage by trade.
- Apply your burden rate (calculated below in the allocation section).
- Multiply by budgeted hours per cost code to get a true labor budget.
Labor, subcontractor costs, and overhead allocation are where most margin problems hide. Materials and permits rarely surprise you; unburdened labor almost always does.
How Do You Set Up Job Costing From Scratch?
Building a job-costing system starts with cost-code design, not software. Get the structure right first, and any tool, from a spreadsheet to an integrated platform, will produce usable numbers.
- Scope your cost codes. Start with categories that mirror your estimate line items: labor, materials, equipment, subs, and overhead. A consistent cost-code structure that mirrors estimate line items is what makes weekly estimate-versus-actual reviews possible.
- Reference a standard framework. Many contractors use MasterFormat/CSI codes to keep coding consistent across trades and projects, especially useful once you’re bidding commercial work with architects and GCs who already speak that language.
- Map codes to your general ledger. Decide which costs hit COGS (direct job costs) versus OPEX (company overhead) so your financials and your job costs reconcile cleanly.
- Choose your granularity. Fewer, broader codes are easier to manage early on.
- Pick a pilot job. Choose a mid-size, well-understood project to test the system before rolling it out company-wide.
Pro Tip: Start with five to seven cost codes per job. Add granularity only after your field crews can reliably enter data against the codes you already have. Extra detail helps on high-dollar, high-risk phases (structural, MEP) and creates noise on small, predictable line items like cleanup or minor hardware.
How Do You Collect Accurate Job-Cost Data in the Field?
Job costing lives or dies on field data quality. If your crews aren’t logging hours and materials against the right cost code daily, everything downstream, from your P&L to your next bid, is built on guesswork.
Practical capture methods that actually work on a job site:
- Mobile time entry tied directly to job and cost code, not just clock in/clock out.
- Photo-based receipt capture at the point of purchase, matched to a purchase order.
- Equipment usage logs recorded by the operator, not reconstructed later from memory.
- Subcontractor invoice intake routed against committed costs, not just paid on submission.
The flow should move from field to review to accounting: a foreman logs hours and materials on-site, a supervisor verifies split-time entries and flags anomalies, and only verified data posts to the accounting system. That sequence catches miscoded entries before they corrupt your reports.
Pro Tip: Build one approval checkpoint where a supervisor reviews entries within 24 hours, not at month-end. Catching a miscoded receipt on Tuesday costs you two minutes. Catching it during month-end close costs you an afternoon and a headache.
How Do You Allocate Overhead and Calculate Labor Burden?
Overhead allocation determines whether your job costs reflect reality or just direct spend. Three methods dominate:
- Percent of revenue. Simple, but distorts numbers when job sizes vary widely.
- Percent of direct cost. Better for contractors with consistent labor-to-material ratios.
- Rate per labor hour. The most accurate for labor-heavy trades, since it ties overhead to the resource actually driving your costs.
For benchmarks, contractors should budget a 5% to 10% contingency for straightforward projects, and overhead often lands around 10 to 11% of direct costs for well-run shops, though your own historical data should be the real test. Labor burden itself commonly runs 20% to 60% depending on trade and benefits structure.
Where possible, prefer hours-based allocation. It ties overhead to the actual resource consumption driving your costs rather than a revenue figure that fluctuates with bid size.
What Software Features Do You Need for Accurate Job Costing?
Software should eliminate the lag between when a cost happens and when you see it, not just digitize your existing spreadsheet. That means evaluating tools on integration depth, not just feature lists.
Look for these capabilities:
- Mobile time tracking tied to cost codes, not just job numbers.
- Expense capture with photo receipts and PO matching.
- Equipment logging that ties usage hours to specific jobs.
- Change order handling that updates the budget automatically, not manually.
- Audit trails showing who entered or edited every cost.
The critical distinction is between summary-only GL sync and full work breakdown sync. A summary sync that only pushes GL totals loses the phase and cost-code detail that makes job costing useful in the first place, leaving you with a company-wide number instead of job-level insight.
| Evaluation Criteria | What to Test in a Pilot |
|---|---|
| Integration with accounting/ERP | Does it preserve cost codes and WBS, or just push totals? |
| Field-to-accounting latency | How many hours between field entry and visible report? |
| Cost code granularity support | Can it handle job, phase, and cost type simultaneously? |
| Field data capture methods | Mobile timesheets, photo receipts, equipment telemetry |
| Payroll and labor-burden handling | Does burden calculate automatically or require manual entry? |
| Reporting depth | Variance, cost-to-complete, and margin by job available? |
Vendors like JobOS Pro, Deltek, Miter, and Procore each approach this differently, so test field latency and mapping fidelity with your own cost codes before committing to any of them, including a tool like JobOS Pro for platforms built to consolidate that data automatically.
Which Reports and KPIs Actually Matter for Job Costing?
A handful of reports carry most of the decision-making weight. If you’re only checking your bank balance, you’re flying blind until it’s too late to correct course.
- Estimate vs. Actual by cost code, which shows exactly where a job is drifting from budget.
- Job Profitability report, giving you a true margin figure per project.
- WIP schedule, tracking billed-to-date against costs incurred.
- Cost Variance report, flagging deviations before they compound.
- Commitments vs. Actuals, comparing what you’ve committed to subs and vendors against what’s posted.
- AR aging by job, since a profitable job on paper still hurts you if payment is 90 days out.
Financial leaders should monitor job profitability, WIP, cost variance, and AR aging as core indicators of company health, not just individual job health.
How Does Job-Cost Data Improve Bidding and Operations?
Job-cost data only pays off when you actually use it to change decisions, not just to explain what already happened.
- Estimate adjustment: feed actual burdened labor rates and material costs back into your next bid.
- Weekly crew productivity reviews: compare budgeted hours per phase against actual hours logged.
- Equipment rent-vs-buy decisions: use utilization data across jobs to see if a piece of equipment justifies ownership.
- Change-order enforcement: require signed change orders before extra work gets logged against the budget.
Instead of waiting for the job to close, they flag it immediately, discover the crew is underbid on square footage, and adjust the next three bids for similar homes before those jobs go out the door.
- Pull the variance report weekly, not monthly.
- Correct the estimate template the same week you find the gap.
What Pitfalls Should You Watch for During Rollout?
The mistakes that wreck job costing are almost always the same five: uncoded receipts, unburdened labor rates, missing overhead allocation, late data capture, and unsigned change orders that get worked anyway.
Controls that stop these before they hit your books:
- Require a job code at the point of time entry or purchase, with no exceptions.
- Run weekly estimate-vs-actual reviews, not monthly.
- Route every entry through a supervisor approval step before it posts.
- Match every vendor invoice against a purchase order before payment.
- Day 1: assign cost-code ownership and lock the code list.
- Week 1: train field crews on mobile entry and require daily submission.
- Month 1: run your first estimate-vs-actual report and correct any drift.
Pro Tip: If a cost hits your books without a job code, reject it at entry rather than fixing it later. Cleanup after the fact costs ten times more than catching it upfront.
How Long Does It Take to Roll Out Job Costing?
A realistic rollout runs in four phases, and rushing any of them is how pilots stall out.
- Planning (1 to 2 weeks): finalize cost codes, GL mapping, and pick your pilot job.
- Pilot setup (2 to 4 weeks): configure the system, train the pilot crew, and test data capture.
- Pilot execution (4 to 8 weeks): run the pilot job through to substantial completion, correcting workflow issues as they surface.
- Full rollout (4 to 12 weeks): extend the system across all active jobs and crews.
Success criteria for the pilot: consistent daily field entries, correct GL mapping with no manual corrections, weekly estimate-vs-actual reports running without gaps, and at least one closed job used to calibrate your burden rates and overhead assumptions.
Assign clear ownership: one person owns the cost-code list, supervisors approve daily entries, and a controller or ops lead monitors the KPIs weekly.
What Do the Benchmarks Say About Contingency and Burden?
The numbers worth anchoring to: budget a 5% to 10% contingency for straightforward projects, and expect labor burden in the 20% to 60% range depending on trade and benefits.
- Test your overhead allocation against at least two years of your own job history before trusting a generic industry percentage.
- Recalculate burden annually, since insurance and workers’ comp rates shift year to year.
Overhead that isn’t systematically allocated distorts every margin number downstream, no matter how accurate your labor and material tracking is.
How Job Costing Looks Different Across Trades and Project Types
Residential remodelers, commercial general contractors, and specialty trades all run job costing through the same core structure, but the workflow details shift.
Residential remodeling projects tend to run shorter cycles with tighter cost-code lists, often five to eight codes covering demo, framing, MEP rough-in, finishes, and cleanup. Because homeowners request scope changes mid-project constantly, change-order discipline matters more here than almost anywhere else. A remodeler who doesn’t capture a client’s mid-job “just add this” request as a signed change order eats that cost directly.
Commercial general contractors manage far more cost codes per job, often mapped closely to CSI/MasterFormat divisions, and need to track multiple subcontractors simultaneously against committed costs. WIP reporting becomes critical here since commercial jobs often span months with progress billing tied to completion percentage.
Specialty trades, plumbing, electrical, and HVAC in particular, tend to run a mix of project work and service calls, which means job costing has to handle both a multi-week installation and a two-hour service ticket under the same system. A plumbing contractor tracking parts and labor on a service call needs the same cost-code discipline as one running a full repipe, just compressed into a shorter window. Similarly, an electrical contractor juggling new construction and service work benefits from cost codes flexible enough to cover both without duplicating the entire structure for each job type.
How Do You Adjust Job Costs When a Project Changes?
Every job drifts from its original budget eventually, whether from a client-requested change, an unforeseen site condition, or a material price spike. The question is whether your system catches that drift fast enough to act on it.
Start by treating any deviation as a trigger for a formal budget revision, not just a note in the file. When a change order comes in, price it against your actual burdened labor and current material costs, not the original bid rates, since those numbers may already be stale. Log the revised budget against the same cost code the original estimate used, so your variance report still compares apples to apples.
For unforeseen costs, like discovering rotted framing behind drywall or hitting rock during excavation, draw from your contingency line first rather than quietly absorbing the hit into another cost code. That keeps your reporting honest about where the money actually went. If the contingency doesn’t cover it, that’s your signal to have the change-order conversation with the client immediately, not after the work is already done.
Waiting until month-end to reflect a known cost increase just delays a decision you could make today. The contractors who protect margin best treat their budget as a living document updated weekly, not a fixed number set at contract signing and revisited only at closeout.
Who Should Own Data Entry, Monitoring, and Analysis?
Job costing fails almost as often from unclear ownership as from bad software. Someone needs to own each stage: entry, review, and analysis, or the system quietly decays back into guesswork within a few months.
Field crews and foremen own data entry. They log hours, materials, and equipment usage daily against the correct cost code, ideally through mobile time entry rather than end-of-week paper timesheets that guarantee errors from memory gaps.
Supervisors and project managers own monitoring. They review entries within 24 to 48 hours, catch miscoded time or missing receipts, and approve entries before they post to accounting. This is also the role that flags a labor variance the moment it appears, rather than discovering it at job close.
Controllers, bookkeepers, or an operations lead own analysis. They run the weekly estimate-vs-actual reports, track WIP schedules, and translate variance data into decisions: reforecast the job, adjust the next bid, or coach a crew on productivity.
Smaller shops often collapse the monitoring and analysis roles into one person, usually the owner or office manager, which works fine as long as that person actually reviews the reports weekly rather than letting them accumulate. The size of your company matters less than whether every role has a named owner who knows the review is their job.
A Publisher’s Perspective on Integrated, AI-Assisted Job Costing
Most job-costing failures I see aren’t math errors. They’re latency problems: a receipt sits in a truck for a week, a timesheet gets reconstructed from memory on Friday, and by the time accounting sees the number, the job that could have been corrected is already closed. Integrated field-to-accounting systems solve this by collapsing that gap, and the fewer hands a piece of data passes through before it hits your report, the fewer chances it has to get miscoded or lost entirely.
What’s underappreciated is what happens at scale across multiple crews or locations. A capability like multi-location intelligence, which flags which crews or branches are consistently hitting labor budgets and standardizes that behavior across a franchise network, does something a single-job report never can: it turns one team’s discipline into every team’s baseline.
How JobOS Pro Supports Real-Time Job Costing
There are other ways to build this system, spreadsheets, standalone time-tracking apps, or a patchwork of tools that don’t talk to each other. Most contractors running that setup discover the gaps only after a job closes at a loss they didn’t see coming.
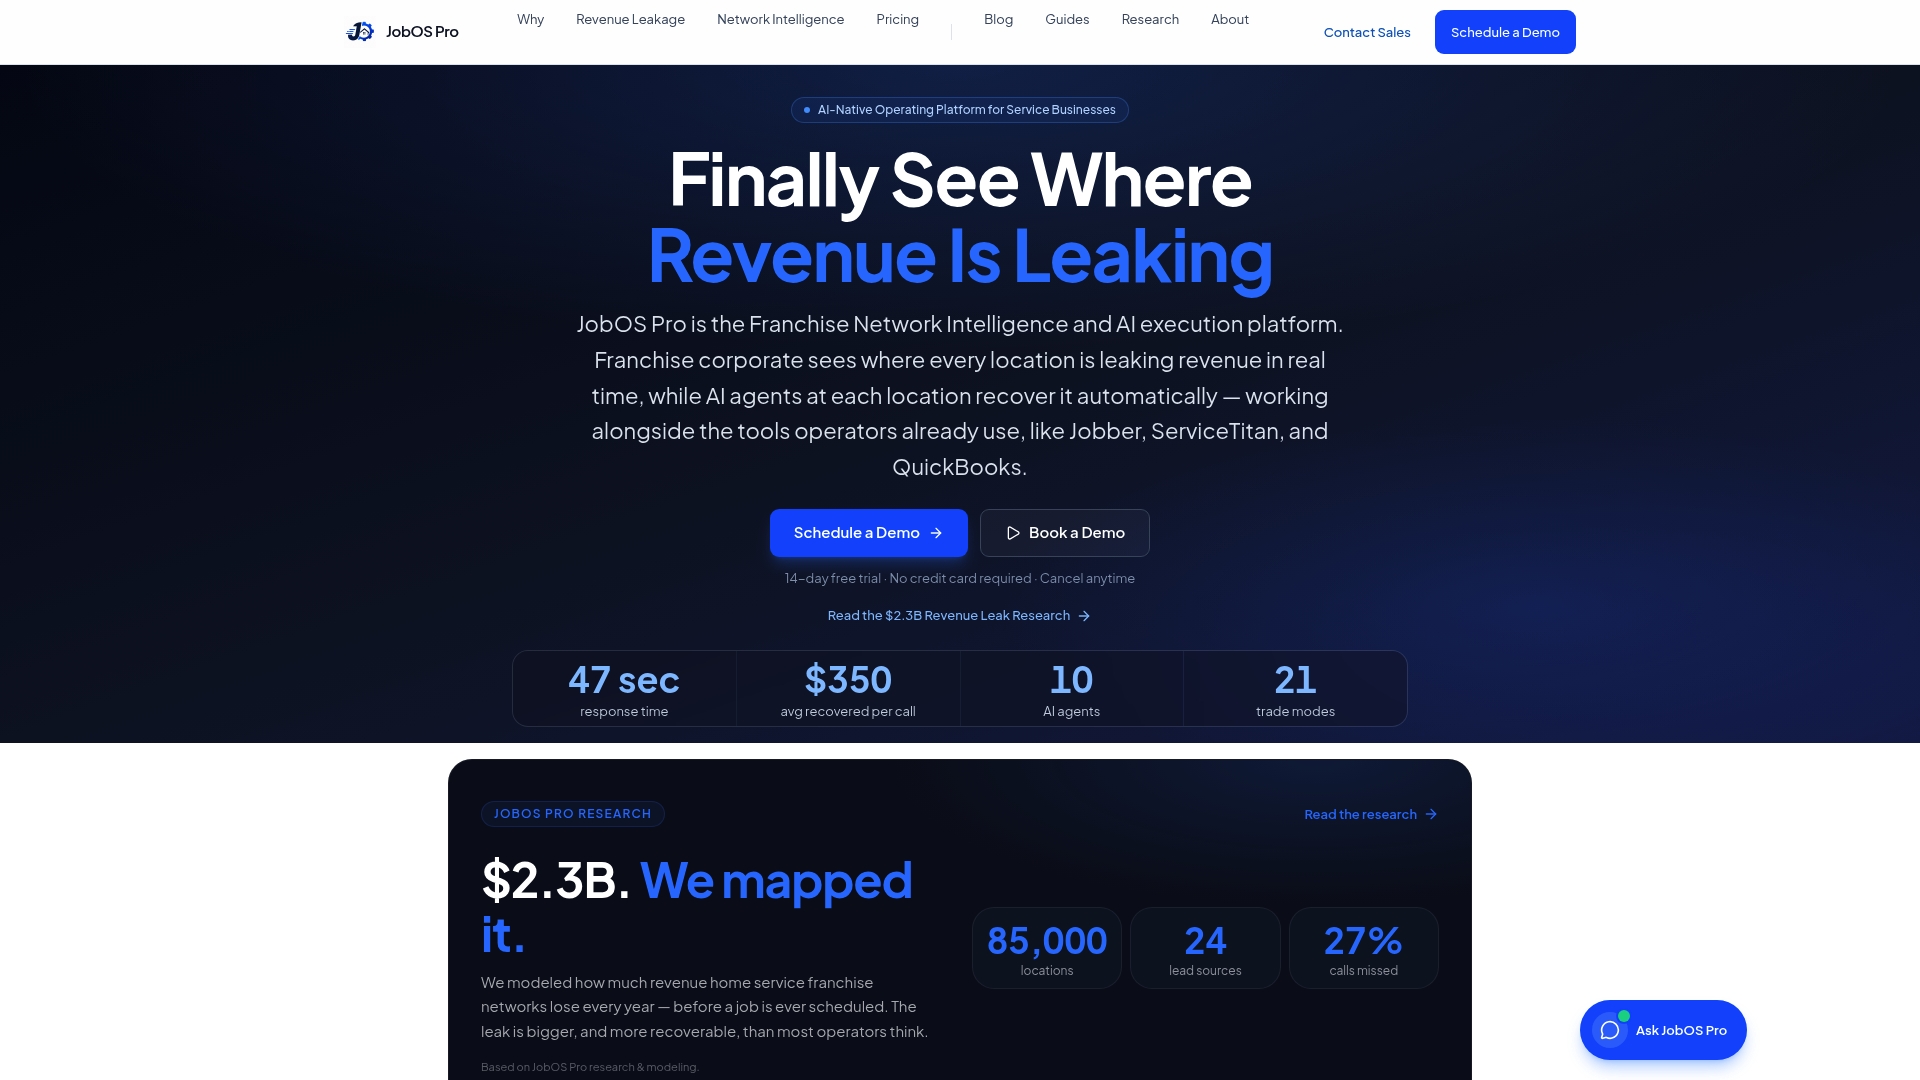
JobOS Pro is built for contractors who want field data to reach accounting the same day it happens, not weeks later. The platform handles mobile field capture tied directly to cost codes, preserves your full work breakdown structure when syncing to your GL rather than pushing summary totals, and integrates with payroll so burdened labor rates calculate automatically instead of by hand. Automated receipt capture and approval routing cut the miscoding that corrupts most job-cost reports, and AI agents surface revenue leaks, missed billable hours, delayed invoicing, uncaptured change orders, before they compound across a job. For franchise operators, multi-location benchmarking shows which branches are hitting their numbers and which need coaching.
That structure maps directly onto the pilot timeline covered above: a two-week planning phase, a focused pilot job, and success criteria you can actually measure. If you’re ready to stop reconciling job costs after the fact, see how JobOS Pro’s features fit your cost-code structure, or start with a pilot on your next active job.
Sources
- Job Costing for Contractors: A Step-by-Step 2026 Guide - Contractor Guide Pro